CU Boulder — EVEN 2909 — Carbon Markets & Climate Finance
← Course Home

Carbon Markets & Climate Finance

EVEN 2909: Introduction to Sustainability Engineering — Week 14

University of Colorado Boulder

The Climate Problem

45%
GHG cut needed by 2030
1.5°C
Paris Agreement target
~42 Gt
CO₂ emitted annually

The IPCC Sixth Assessment Report (2023) is unequivocal: global greenhouse gas emissions must fall 45% below 2010 levels by 2030 and reach net-zero by 2050 to limit warming to 1.5°C.

Current national pledges (NDCs) put us on track for roughly 2.5–2.8°C of warming by 2100. The gap between ambition and action is enormous.

The core question: How do we create economic incentives large enough to close this gap?

Source: IPCC AR6 Synthesis Report, 2023

The Economic Logic

“Climate change is the greatest market failure the world has ever seen.” — Nicholas Stern, The Economics of Climate Change, 2006

Carbon dioxide is an externality — the cost of climate damage is not reflected in the price of fossil fuels. Putting a price on pollution creates incentives to reduce it.

Two key mechanisms:

  • Polluter pays: Emitters internalize the social cost of carbon (~$51/tonne, US EPA estimate)
  • Least-cost abatement: Markets find the cheapest reductions first, lowering the overall cost of climate action

Without a carbon price, there is no financial incentive to choose a cleaner option when a dirtier one is cheaper.

Three Approaches to Carbon Pricing

Carbon Tax

Price certainty
Government sets the price per tonne of CO₂. Emitters decide how much to reduce.
  • Simple to implement
  • Predictable costs for industry
  • No guarantee on total emissions
  • Examples: Canada ($65 CAD/t), Sweden ($130/t)

Cap-and-Trade

Quantity certainty
Government caps total emissions, distributes allowances. Companies trade them.
  • Guarantees emission limit
  • Price fluctuates with market
  • Risk of over-allocation
  • Examples: EU ETS, CA cap-and-trade, RGGI

Voluntary Offsets

No regulation
Companies voluntarily buy credits to “offset” their emissions from verified projects.
  • Buyer-driven, no government mandate
  • Funds projects in developing countries
  • Integrity depends on project quality
  • Examples: Gold Standard, Verra VCS

The Precedent: Ozone and the First Pollution Markets
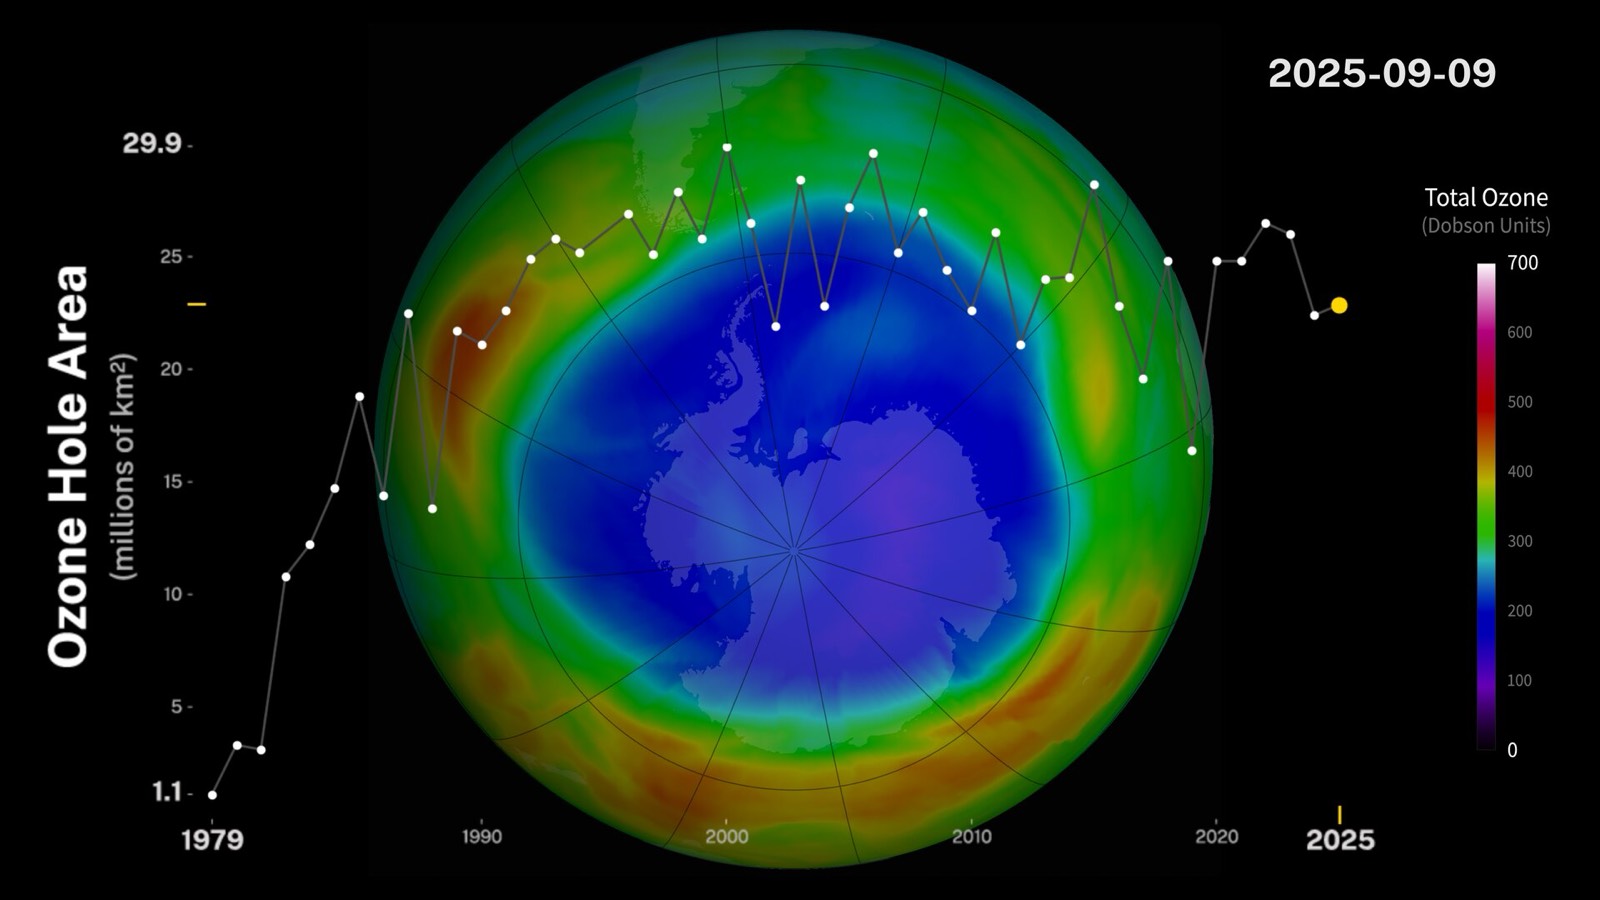
Globe centered on Antarctica showing low ozone in blue and purple, with a chart of the ozone hole's maximum area each year from 1979 to 2025 rising until the 2000s and then leveling off
Antarctic ozone hole and its yearly maximum area, 1979–2025. NASA SVS, public domain.
1974Molina and Rowland show CFC chlorine can destroy stratospheric ozone.
1985Large springtime ozone losses reported over Antarctica.
1987Montreal Protocol signed; in 2009 it becomes the first UN treaty ratified by every country.

The first pollution markets

CFC allowances. To meet the Protocol, EPA gave each CFC producer and importer tradable allowances. The total shrank on a schedule until production ended, in 1996 for most CFCs.

Acid Rain Program (1990). Power plants traded sulfur dioxide allowances under a cap and found the cheapest cuts.

5.7 Mt
SO2 in 2009, under a 9.5 Mt cap
>40:1
Benefits to costs (EPA)

Why carbon is harder

CFCsCO2
Who emitsA few chemical producersEvery plant, vehicle, farm and furnace
SubstitutesWithin yearsFor some uses; others decades away
Share of economySmallMost of the world’s energy

Ozone returns to 1980 levels around 2040 for most of the world and 2066 over Antarctica. The 2016 Kigali Amendment on HFCs is expected to avoid 0.3–0.5 °C of warming by 2100.

Sources: Molina & Rowland (1974), Nature 249:810; Farman et al. (1985), Nature 315:207; UNEP Ozone Secretariat; EPA ozone allowance rules (Federal Register 1995, 2003); EPA Acid Rain Program 2009 Highlights; WMO/UNEP Scientific Assessment of Ozone Depletion: 2022.

The First Pollution Markets

CFC production allowances

To meet the Montreal Protocol, the US EPA gave each producer and importer of CFCs a baseline number of production and consumption allowances. Companies spent an allowance for each unit they made or imported, and could trade them. The total shrank on a schedule until production ended, in 1996 for most CFCs. EPA later used the same system for HCFCs.

Acid Rain Program (1990)

The 1990 Clean Air Act Amendments capped sulfur dioxide from power plants and let them trade allowances. Plants found the cheapest cuts: scrubbers, low-sulfur coal, fuel switching.

5.7 Mt
SO2 emitted in 2009, under a 9.5 Mt cap
>40:1
Benefits to costs (EPA)

Compliance cost far less than predicted when the law passed.

These were the working examples of emissions trading when the Kyoto Protocol (1997) created international carbon trading and the Clean Development Mechanism.

Sources: EPA, Protection of Stratospheric Ozone allowance rules (Federal Register 1995, 2003); EPA, Acid Rain Program 2009 Highlights and Acid Rain Program Results.

Why Ozone Was Easier Than Carbon

CFCsCO2
Who emitsA small number of chemical producersEvery power plant, vehicle, farm and furnace
SubstitutesAvailable for most uses within yearsAvailable for some uses; others decades away
Share of the economySmallFossil fuels supply most of the world’s energy
HarmSkin cancer and crop damage, worldwideClimate damage, unevenly spread and delayed

The payoff

If current policies hold, total ozone returns to 1980 levels around 2040 for most of the world, 2045 over the Arctic and 2066 over Antarctica.

And a climate dividend

The 2016 Kigali Amendment extends the Protocol to HFCs, the CFC replacements that are potent greenhouse gases. It is expected to avoid 0.3–0.5 °C of warming by 2100.

Ask: which features of the ozone problem could a carbon market reproduce, and which can it not?

Source: WMO/UNEP Scientific Assessment of Ozone Depletion: 2022, Executive Summary.

A Brief History of Carbon Markets

1997
Kyoto Protocol
→
2005
CDM Launches
→
2005
EU ETS Begins
→
2015
Paris Agreement
→
2021
Article 6 Rules
→
2023
ICVCM Principles

Kyoto Era (1997–2020)

  • Clean Development Mechanism (CDM): First global offset system — developed-country emitters fund projects in developing countries
  • Issued 2+ billion CERs (Certified Emission Reductions)
  • Criticized for weak additionality and verification

Paris Era (2015–present)

  • Article 6: Creates new international carbon market rules under the Paris Agreement
  • Voluntary carbon market grows independently alongside compliance systems
  • Integrity crisis in 2023 drives reforms (ICVCM, VCMI)
Section 1

How Carbon Credits Work

From project concept to retired credit

What Is a Carbon Credit?

1 carbon credit = 1 metric tonne of CO₂e avoided or removed from the atmosphere

Avoidance Credits

Prevent emissions that would have occurred in a business-as-usual scenario.

  • Renewable energy replacing coal
  • Safe water replacing wood-fuel boiling
  • Efficient cookstoves reducing biomass use
  • Avoided deforestation (REDD+)

Removal Credits

Physically remove CO₂ already in the atmosphere.

  • Afforestation / reforestation
  • Direct air capture (DAC)
  • Biochar
  • Enhanced weathering

Removal credits typically command higher prices ($50–$600+/t) due to stronger climate claims.

The Carbon Credit Project Cycle

1. Develop
Design project &
write PDD
→
2. Validate
Third-party auditor
reviews design
→
3. Implement
Build & operate
the project
→
4. Monitor
Collect data on
emission reductions
→
5. Verify
Auditor confirms
reductions occurred
→
6. Issue
Registry issues
serialized credits

Key insight: This cycle takes 2–4 years from project design to first credit issuance. The upfront cost and timeline are major barriers for project developers, especially in low-income countries.

PDD = Project Design Document. Each credit receives a unique serial number on the registry.

Key Integrity Concepts

Additionality
Would the emission reduction have happened anyway without the carbon credit revenue? If yes, the project is not additional — and the credit is worthless. This is the single most debated concept in carbon markets.
Baseline
What would emissions have been without the project? The baseline scenario determines how many credits are generated. Setting it too high = over-crediting.
Permanence
Will the carbon stay out of the atmosphere? A forest can burn down. A DAC facility stores CO₂ in rock. Permanence risk varies enormously by project type.
Leakage
Does protecting one forest just push logging to the next forest over? Leakage means the emission reduction shifts elsewhere rather than being truly eliminated.

Carbon Credit Registries

Registries are the institutions that set standards, review projects, and issue/track credits. They are the backbone of market integrity.

Verra (VCS)
Largest voluntary registry. ~75% of voluntary market credits. Verified Carbon Standard. Headquarters: Washington, DC.

1+ billion credits issued to date

Gold Standard
Founded by WWF. Emphasizes co-benefits (health, livelihoods). Strong SDG alignment. Popular for cookstove & water projects.

Requires water quality monitoring for safe water credits

CDM / Article 6.4
UN-managed. Legacy Kyoto mechanism transitioning to new Paris Agreement framework under Article 6.4 Supervisory Body.

Transitioning from CERs to A6.4ERs

Carbon Credit Project Types

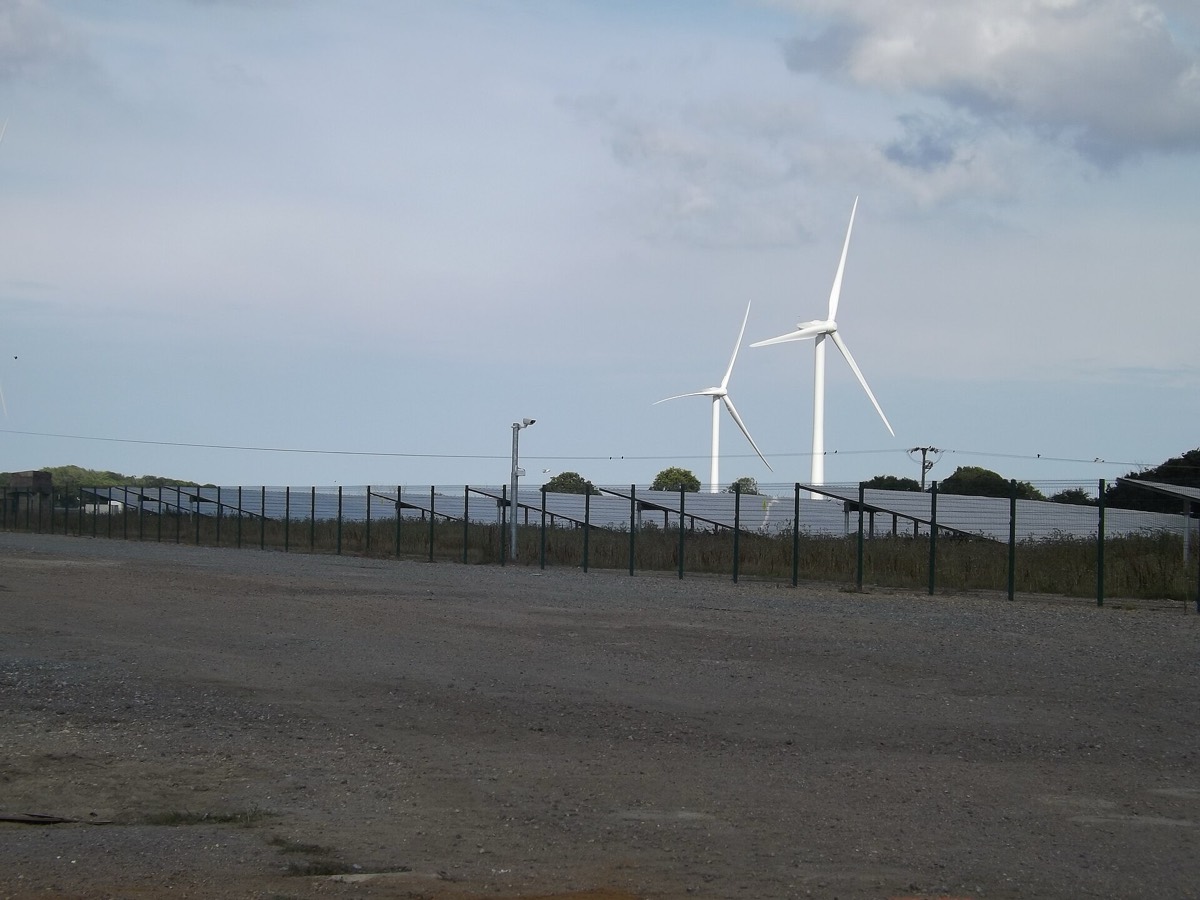
Wind turbines and solar panels
EstablishedRenewable energySolar, wind and hydro displacing fossil generation. Largest category historically; additionality is hard to show now that renewables are often the cheapest option.
Aerial view of the Amazon rainforest and a river
EstablishedForestry & REDD+Protecting existing forests or planting new ones. High permanence and leakage risk.
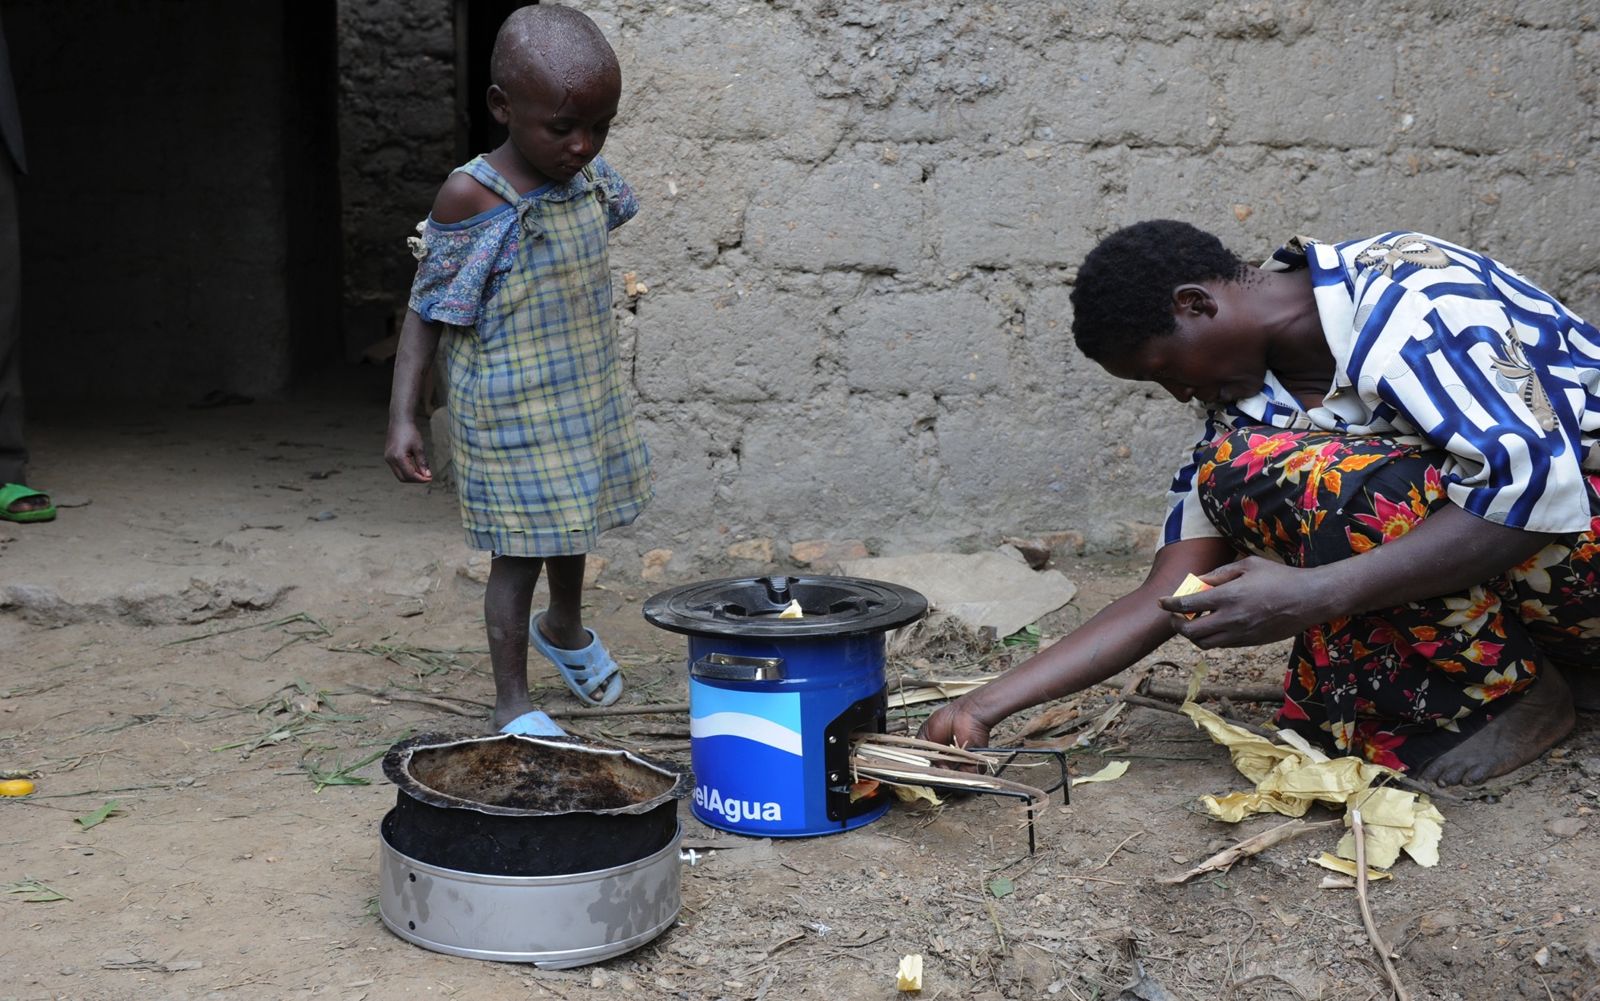
An improved cookstove in a Rwandan kitchen
EstablishedCookstovesEfficient stoves burn less wood or charcoal. Health benefits from cleaner indoor air.
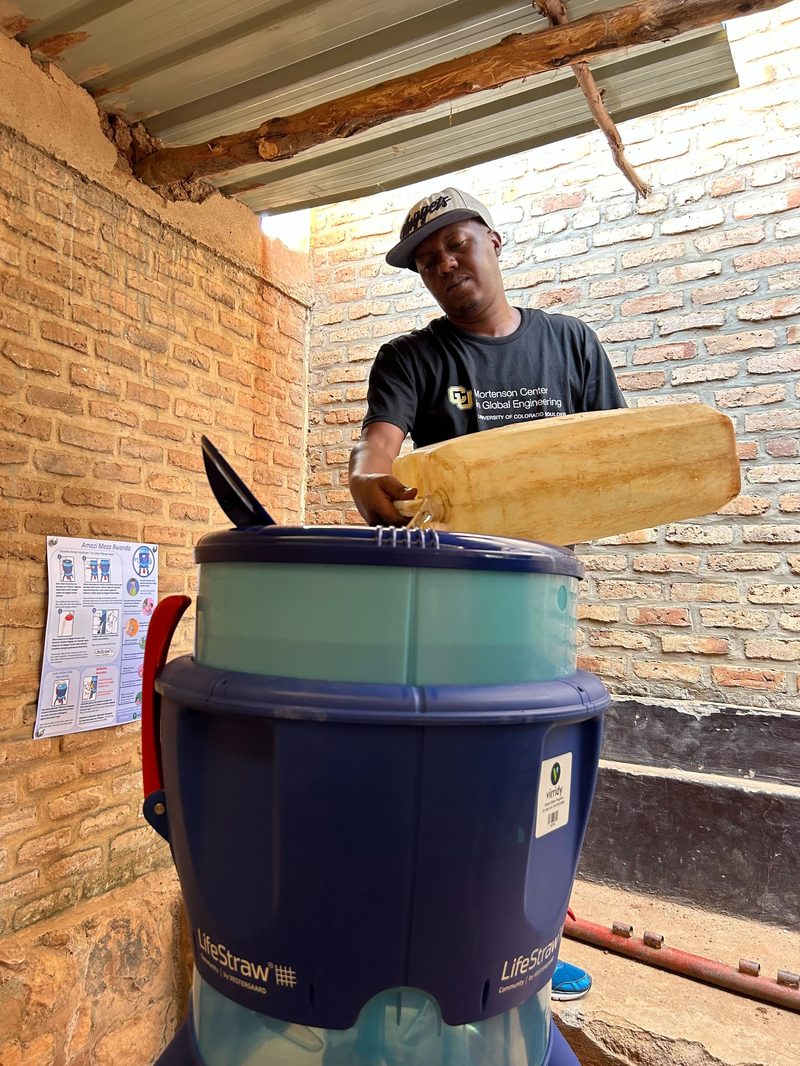
A community water filter being filled at a school
EmergingSafe drinking waterTreated water replaces water boiled over wood fires. Credits require proof the water is safe.
Equipment working the face of a landfill
EmergingMethane captureLandfill gas, coal mine methane, manure. Methane traps about 80 times as much heat as CO2 over 20 years.
Mangrove trees with exposed roots on a Tanzanian shore
EmergingBlue carbonMangrove, salt marsh and seagrass restoration. Measurement science still developing.
CO2 → rock
EmergingDirect air captureMachines pull CO2 from air for underground storage. Near-permanent, but costly ($400–600+/t).
A hayfield with subsurface drip irrigation next to a center pivot field
EmergingAgricultural land managementPractices like drip irrigation and reduced fertilizer that cut nitrous oxide or add soil carbon.

Photos: Upper Holton wind & solar farm, UK (Geographer, CC BY-SA 2.0); Amazon near Manaus (lubasi, CC BY-SA 2.0); mangroves, Tanzania (Fatih Renkligil, CC BY-SA 4.0); subsurface drip, Texas (USDA NRCS, public domain); others from course photo library.

Section 3

The Water–Carbon Connection

Where sustainability engineering meets climate finance

Water Sector = 10% of Global Emissions

The global water sector — including supply, treatment, distribution, and wastewater — accounts for roughly 10% of global greenhouse gas emissions, yet receives less than 2% of carbon finance.

1.6 billion credits/year could be generated from the water sector alone — equivalent to roughly 1.6 Gt CO₂e annually.

Most of this potential is in low- and middle-income countries where 2 billion people lack safely managed drinking water.

Source: Thomas et al., “Decarbonizing Water,” ACS ES&T Water, 2024

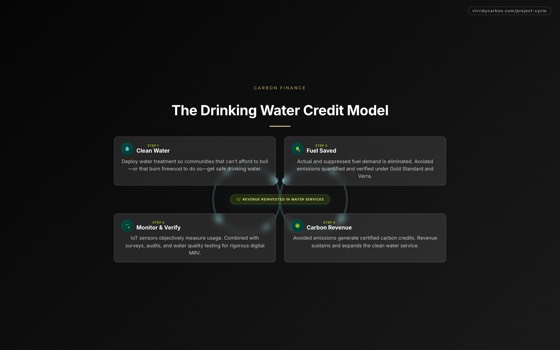
The Drinking Water Credit Model

Virridy’s approach: an infinity loop connecting water access to climate finance

WATER CARBON FINANCE 1 Deploy water treatment 2 Families stop boiling 3 Monitor with sensors 4 Sell credits, reinvest

The key innovation: Carbon credit revenue funds ongoing water treatment — creating a self-sustaining cycle where climate finance pays for clean water, and clean water generates climate finance.

Suppressed Demand Explained

Why can you claim carbon credits for fuel that people are not currently burning?

In many communities, people cannot afford to boil water even though they know it is unsafe. They drink contaminated water instead. This is called suppressed demand.

The logic:

  • Basic service level: Everyone deserves access to safe drinking water (SDG 6)
  • If they could afford fuel, they would boil — so the emissions are suppressed, not absent
  • Providing treatment meets the same need without any fuel, generating legitimate avoidance credits
  • Carbon methodologies allow claiming credits for both actual fuel use displaced and suppressed fuel demand satisfied

Without suppressed demand: Only the wealthiest communities (those already boiling) generate credits — the poorest communities are excluded from climate finance entirely.

Gold Standard Methodology for Water Purification, v2.0

The Evidence

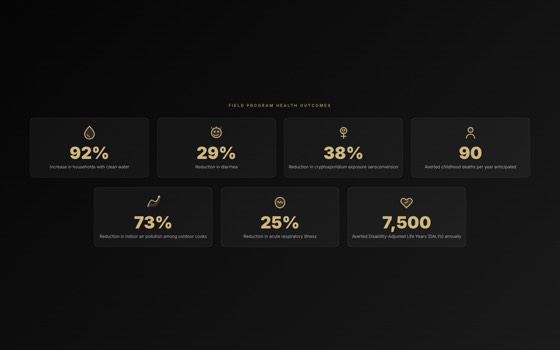
29%
Diarrhea reduction
97.5%
Contamination reduction
36–40%
Self-report overestimate
24/7
IoT monitoring

Health Impact

Point-of-use water treatment reduces diarrheal disease by 29% across populations.

Lancet systematic review

Chlorine dispensers at water collection points achieve 97.5% reduction in E. coli contamination at the point of consumption.

Kirby et al., PLOS ONE

The Monitoring Problem

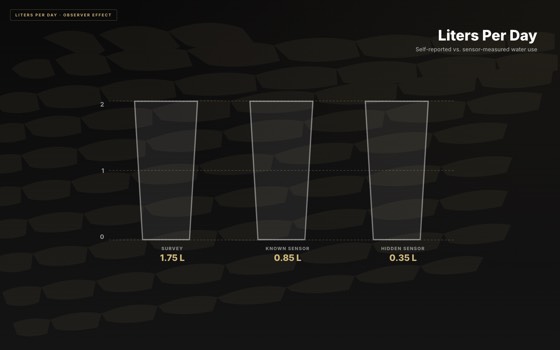
IoT sensor data consistently shows actual usage is 36–40% lower than self-reported usage in surveys.

This is not fraud — it is courtesy bias, recall bias, and aspirational reporting. But it means self-reported data systematically over-credits.

Objective, continuous monitoring is essential for market integrity.

Thomas et al., multiple studies using Lume sensor data

Section 4

Case Study: Virridy

Carbon finance for drinking water, irrigation and the buildings that buy the credits

Disclosure: Prof. Thomas founded Virridy and is its CEO. Read these slides with that in mind, and ask hard questions.

Where Virridy Works

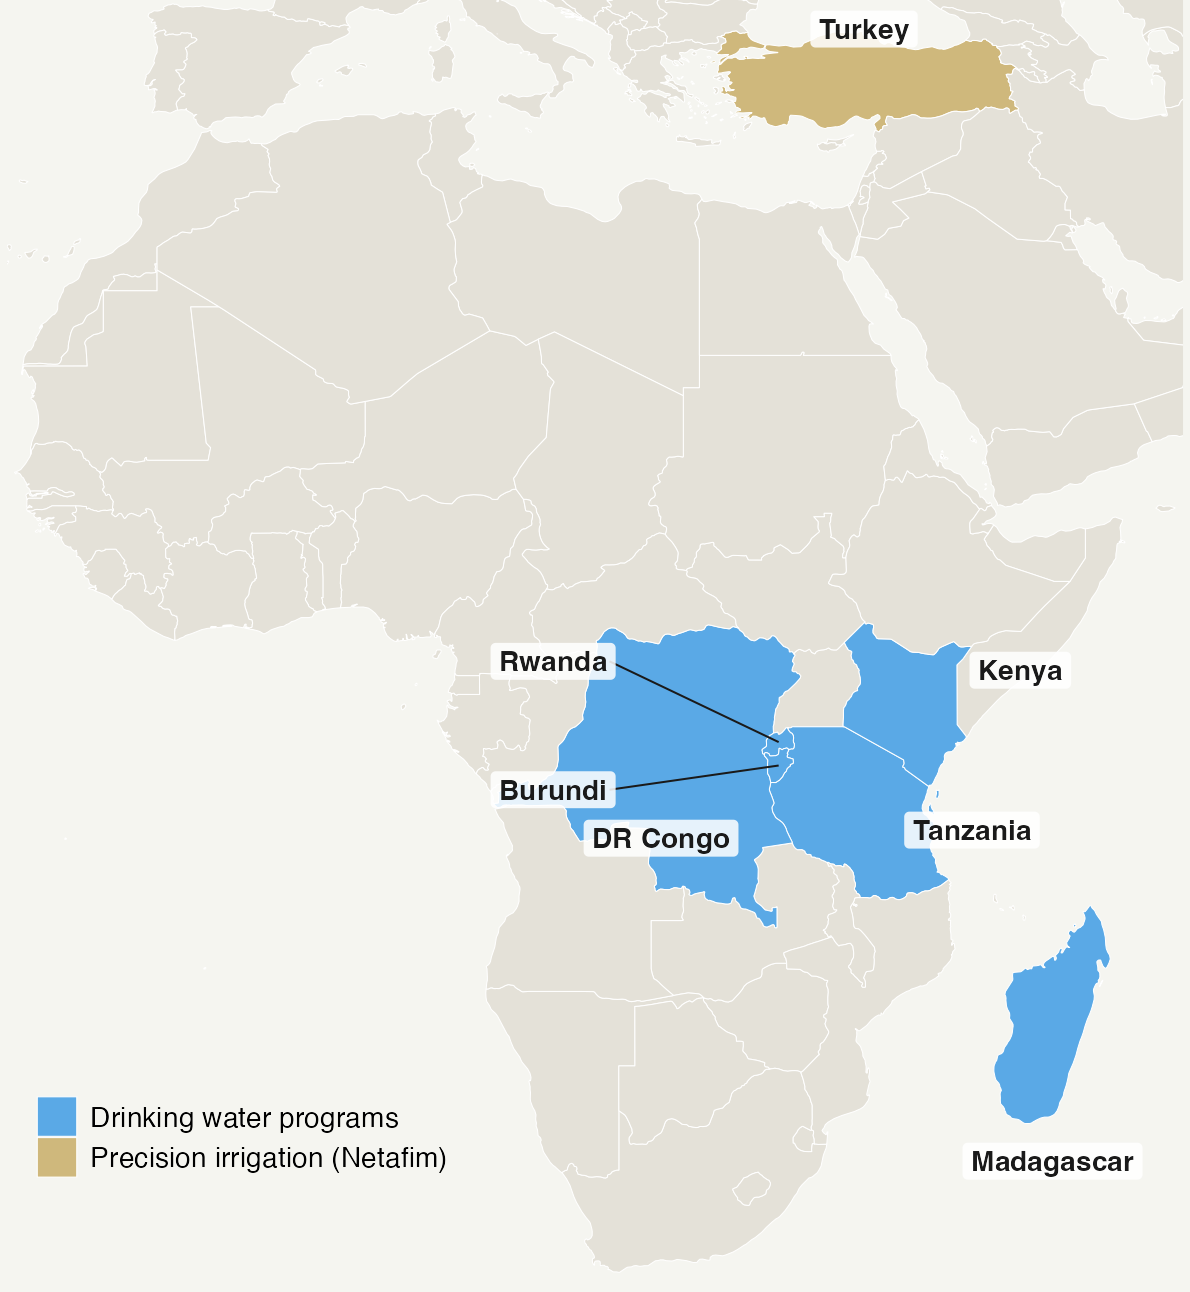
Map of Africa and Turkey with Rwanda, Kenya, DR Congo, Burundi, Tanzania and Madagascar highlighted in blue for drinking water programs and Turkey in gold for precision irrigation
Drinking water: six countries, seven programs
Rwanda, Kenya (two programs), DR Congo, Burundi, Tanzania and Madagascar. Credits come from water treatment that replaces boiling over wood and charcoal fires.
Agriculture: Turkey
Subsurface drip irrigation with Orbia Netafim (below), credited for lower nitrous oxide and more soil carbon.
United States
Headquarters in Boulder; the Lume water-quality sensor and “watershed carbon” methodology development.

Virridy’s programs have delivered clean water to more than five million people since 2007.

Map: Natural Earth boundaries. Sources: Virridy press release (16 Sep 2025); virridycarbon.com.

From One Project to a Portfolio

2007Evan Thomas implements the first UN Clean Development Mechanism and Gold Standard program to earn carbon credits from water treatment.
2012–16Rwanda (Tubeho Neza): water filters and cookstoves for 101,000+ households in Western Province, financed by carbon credits. A randomized evaluation finds 29% less child diarrhea and 25% less respiratory infection.
2022SweetSense renames itself Virridy and raises a $5.5M Series A. Partnership with the Millennium Water Alliance and CU Boulder on Kenya’s drought-resilience program.
2023Amazi Meza school water program launches in Rwanda. M.A. Mortenson Companies pre-purchases credits covering at least 50,000 t CO2e ($2M).
2024First Gold Standard verification for Rwanda: 16,153 t CO2e certified.
2025Programs added in Madagascar, DR Congo, Burundi and Turkey. Rwanda authorizes the project under Article 6.2. Gold Standard approves Virridy’s digital monitoring pilot. Mortenson invests $3M in equity; NSF contracts up to ~$5M.

Sources: Virridy press releases (2022–2025); Kirby et al. (2019), PLOS Medicine 16:e1002812; Gold Standard registry, GS12240.

The Drinking Water Portfolio

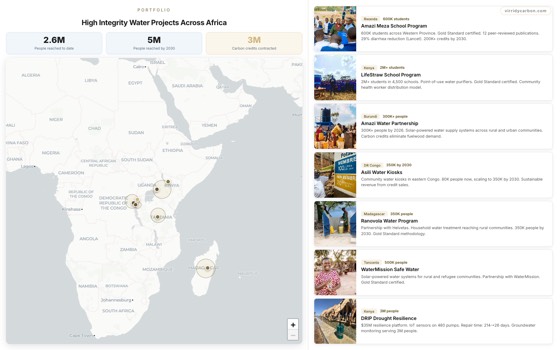
Seven programs in six African countries, each run by a local or international water provider. Virridy develops, monitors and sells the credits under Gold Standard’s Safe Drinking Water Supply methodology; the revenue pays for operations and maintenance.

CountryProgram and implementerTechnologyScale (public figures)
RwandaAmazi Meza (Virridy Rwanda, with the Ministry of Education)Filters in schools500+ schools, ~600,000 students; 1,500 schools by 2028
KenyaDRIP-FUNDI (Millennium Water Alliance)Monitored boreholes~120,000 people, 200 boreholes, 5 northern counties
KenyaLifeStraw school programCommunity filters in schoolsUp to 4,500 schools
DR CongoAsili (Eastern Congo Initiative)Water kiosks, South Kivu~80,000 people; 650,000 by 2029
BurundiAmazi WaterSolar-powered boreholes1,100+ systems nationally
MadagascarRanovola (Helvetas)Gravity and solar piped water~100,000 users; 350,000 by 2030
TanzaniaWater MissionSolar pumping and treatment18 Gold Standard-certified communities

Sources: Virridy press releases and program pages (virridycarbon.com), 2025–2026. Scale figures are each implementer’s, not all credited.

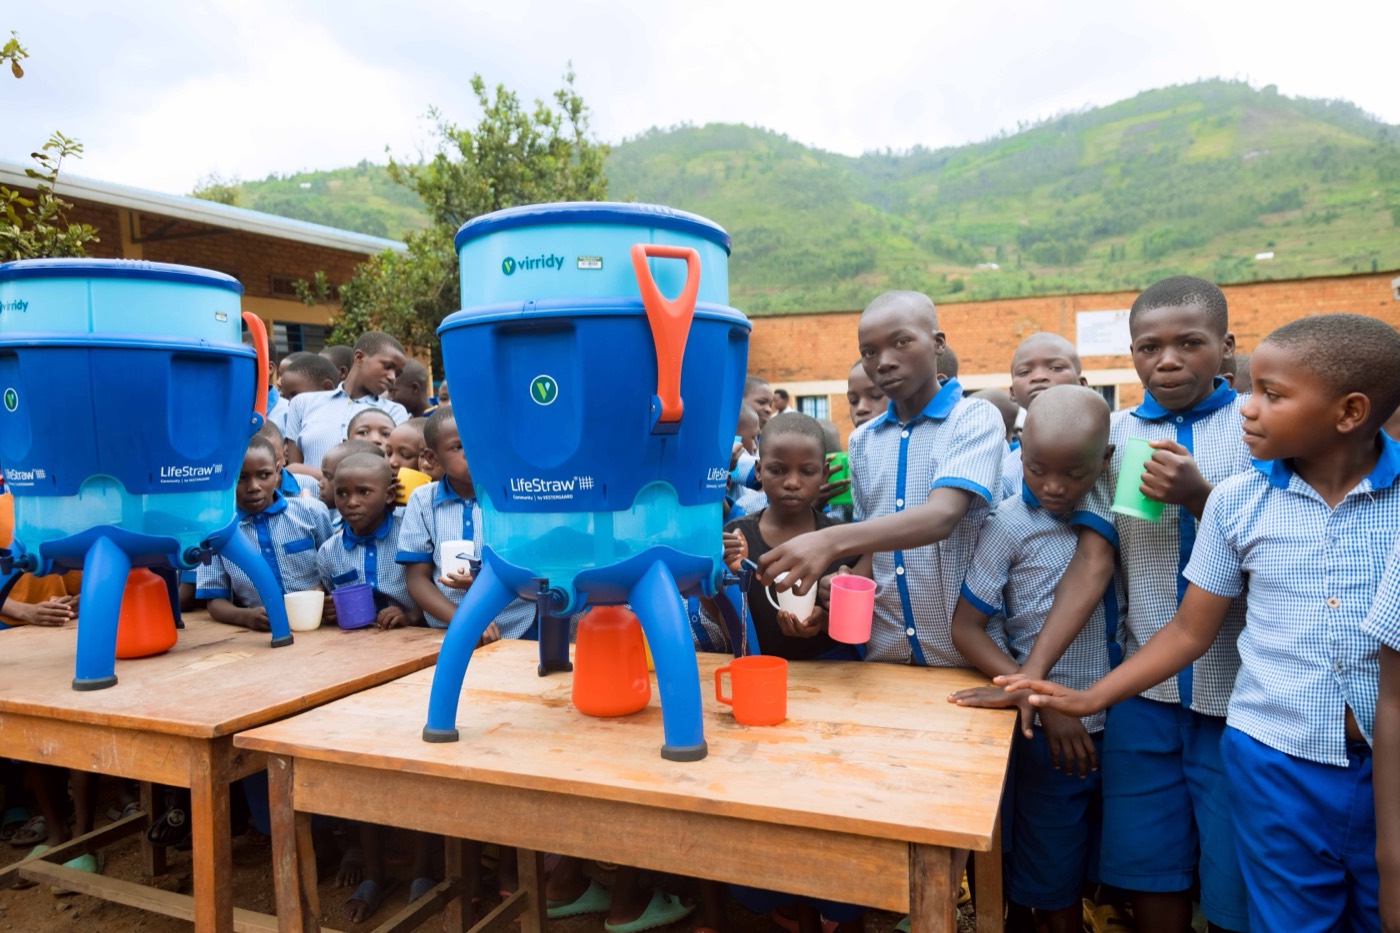
Rwanda: Water in Every School

Students at a Rwandan school filling cups from blue community water filters on a table
Amazi Meza school filters, Rwanda. Photo: Virridy.
The program
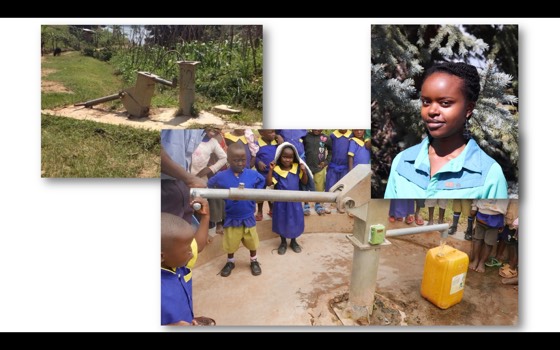
Launched in 2023 with the Ministry of Education. Filters at each school give students treated water without boiling it over wood fires, and water is tested where students drink it.
The credits
Gold Standard project GS12240. First verification: 16,153 t CO2e certified in September 2024.
Article 6.2 authorization (July 2025)
The Rwanda Environment Management Authority authorized over 700,000 t CO2e over five years as internationally transferable, with a corresponding adjustment: Rwanda will not also count these reductions toward its own climate target. That makes the credits eligible for compliance uses such as CORSIA, the aviation scheme.

Sources: Virridy press release (28 Jul 2025); Gold Standard registry GS12240; virridycarbon.com/rwanda.

Kenya: Keeping Boreholes Running
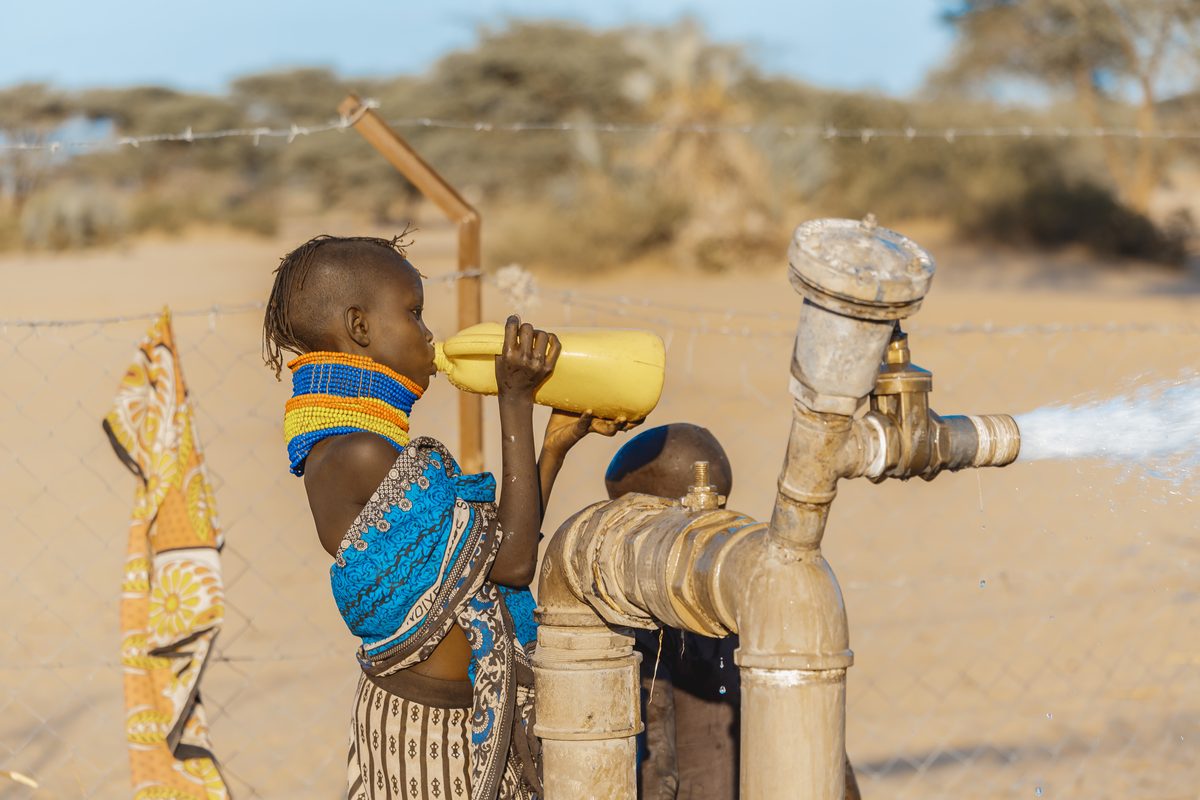
A child drinking from a yellow jerry can at a borehole tap in northern Kenya
Borehole, northern Kenya.
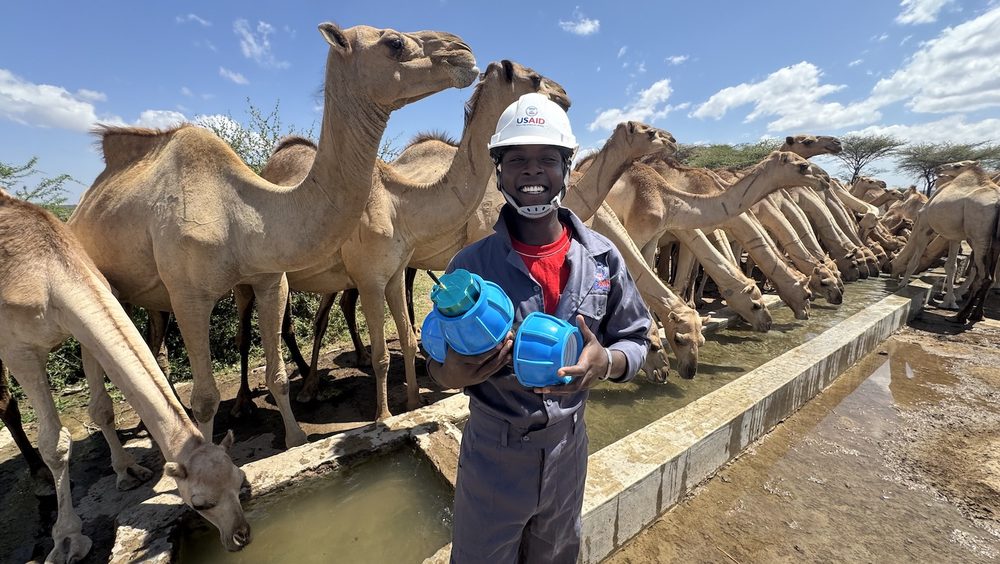
A technician holding sensor housings beside camels drinking at a trough
Field technician with pump sensors.

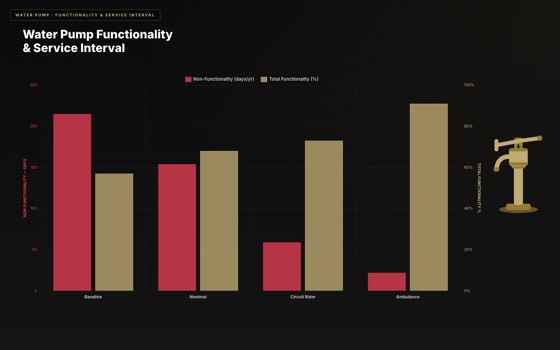
In arid northern Kenya, a broken borehole pump can leave a community without water for months during a drought. DRIP-FUNDI puts satellite- and cellular-connected sensors on the pumps and uses satellite data and machine learning to forecast demand.

214 → 26
Days to repair a failed pump
56% → 91%
Boreholes working

Carbon credits from treated water fund the maintenance teams after the donor grant ends; over 70% of the revenue goes to pump maintenance. Partners include the Millennium Water Alliance, Kenya’s National Drought Management Authority, USAID and NASA.

Sources: virridycarbon.com/kenya-drip; Thomas et al. (2020, 2021) and Fankhauser et al. (2022), Science of the Total Environment.

Four More Countries, Four Models
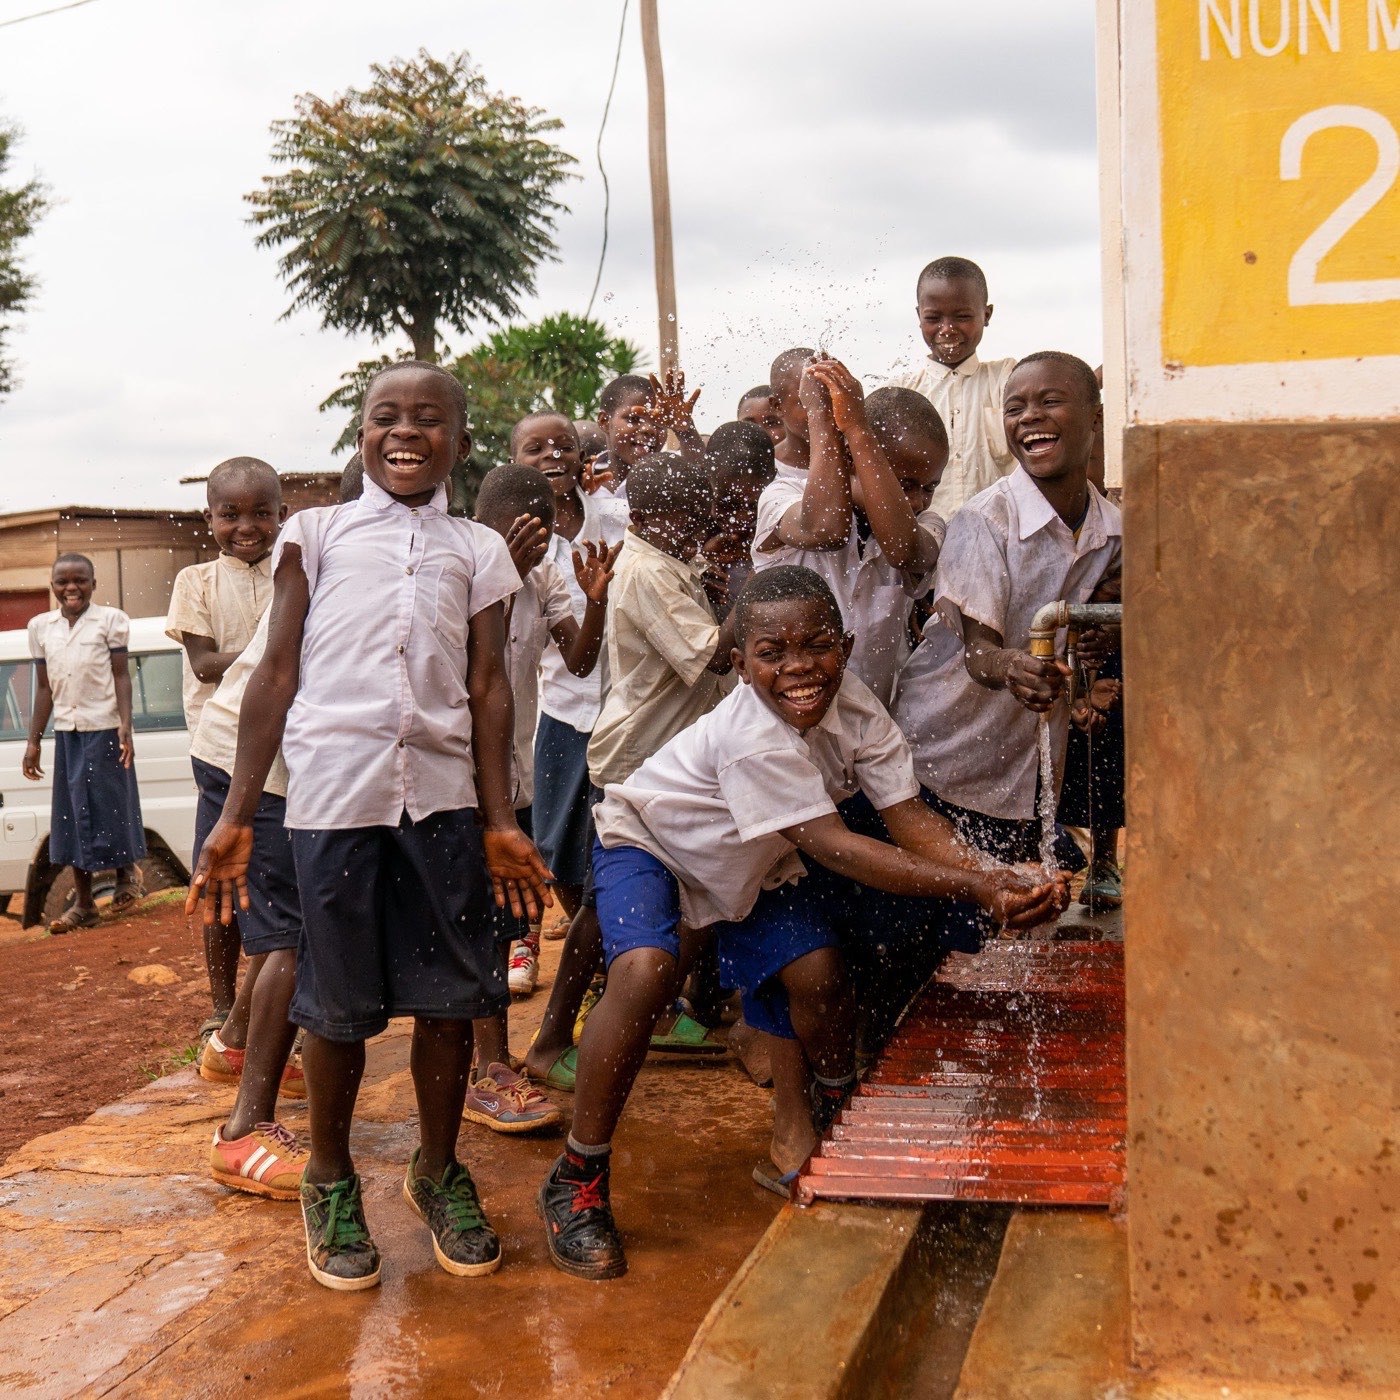
Children washing their hands at a water kiosk tap in eastern DR Congo
Asili water kiosk, South Kivu, DR Congo. Photo: Asili / Virridy.
DR Congo: Asili kiosks
A Congolese social enterprise, co-designed with mothers in South Kivu, that sells water through kiosks run by local women. Self-financing since 2019; carbon revenue funds expansion in a conflict zone where aid is unreliable.
Burundi: Amazi Water
A Burundian social enterprise running solar-powered boreholes in all 18 (historic) provinces, central to the national universal-access plan. Projected to add 300,000+ people by 2026.
Madagascar: Helvetas
Piped gravity and solar systems with private operators in three regions.
Tanzania: Water Mission
Solar pumping and treatment in rural communities and refugee settlements. Carbon program since 2021; 18 communities now Gold Standard-certified.

Sources: Virridy press releases (Mar, Jun, Sep 2025); virridycarbon.com program pages.

Does the Water Get Safer?

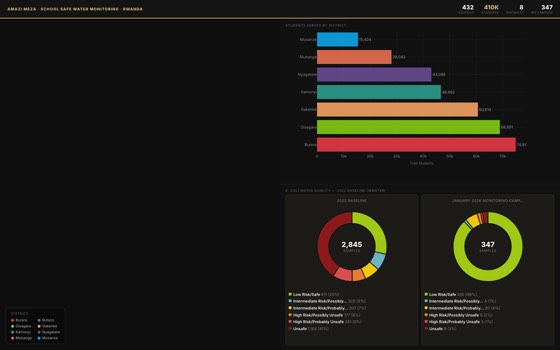
Crediting requires testing water for E. coli where people drink it, before the program and every year after. Across seven programs, 8,373 tests:

Share of samples with E. coli, before → after

Kenya boreholes (MWA)
77% → 7%
Madagascar households
93% → 18%
DR Congo (first monitoring)
95% → 0%
Burundi systems
100% → 0%

■ baseline   ■ after

At baseline, 76.8% of 5,678 samples contained E. coli.

In the school programs, the odds of “very high risk” water fell by about 99%.

In Kenya and Madagascar, the first monitoring rounds showed the implementers that water they thought was safe was not. They added in-line chlorination and operators, cleaned systems and retrained staff.

In northern Kenya, carbon revenue pays the pump repair teams after donor grants end; over 70% of it goes to maintenance.

The argument of the paper: requiring proof before payment is what made the providers fix their systems.

Source: Ecklu, Nagel, MacDonald & Thomas, Tying payment to proof: verification requirements in carbon-financed water projects improve drinking water safety, manuscript under review (2026). Kenya and Madagascar figures span several monitoring rounds. Kenya maintenance: virridycarbon.com/kenya-drip.

Digital Monitoring, Reporting and Verification

How credits are issued

Baseline test
Is the source unsafe?
→
Annual sample
Treated water at the point of use
→
Credits
Scale with the share that pass
Gold Standard dMRV Pilot 14 (September 2025)
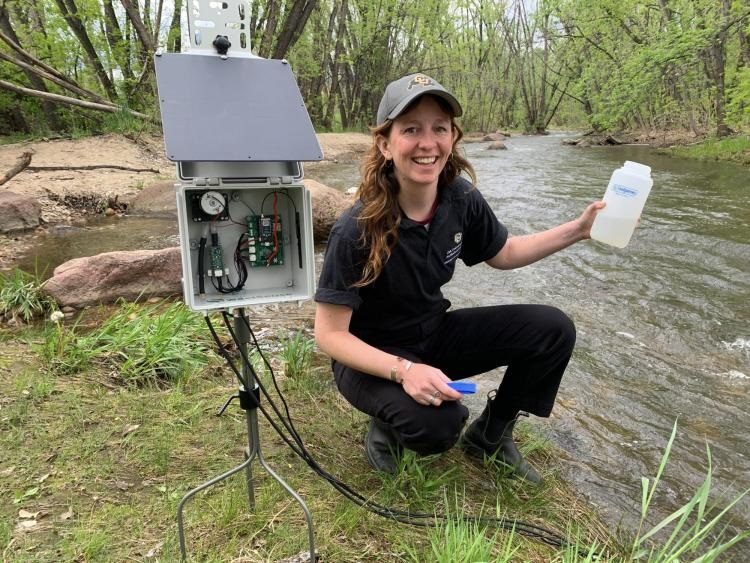
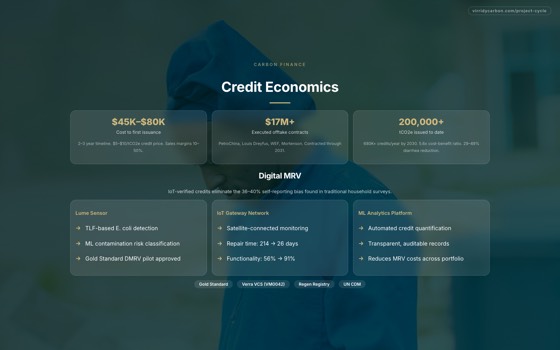
Approved Virridy’s sensor-based monitoring of Rwanda’s school systems in place of periodic site visits: daily timestamped records of water supplied, automated anomaly flags, more than 98% of device data captured.
A researcher beside a solar-powered sensor station at a river, holding a water sample bottle
A Lume water quality sensor station in the field.

Sources: Gold Standard, Safe Drinking Water Supply methodology; Virridy press release (4 Sep 2025).

Turkey: Carbon Credits From Drip Irrigation

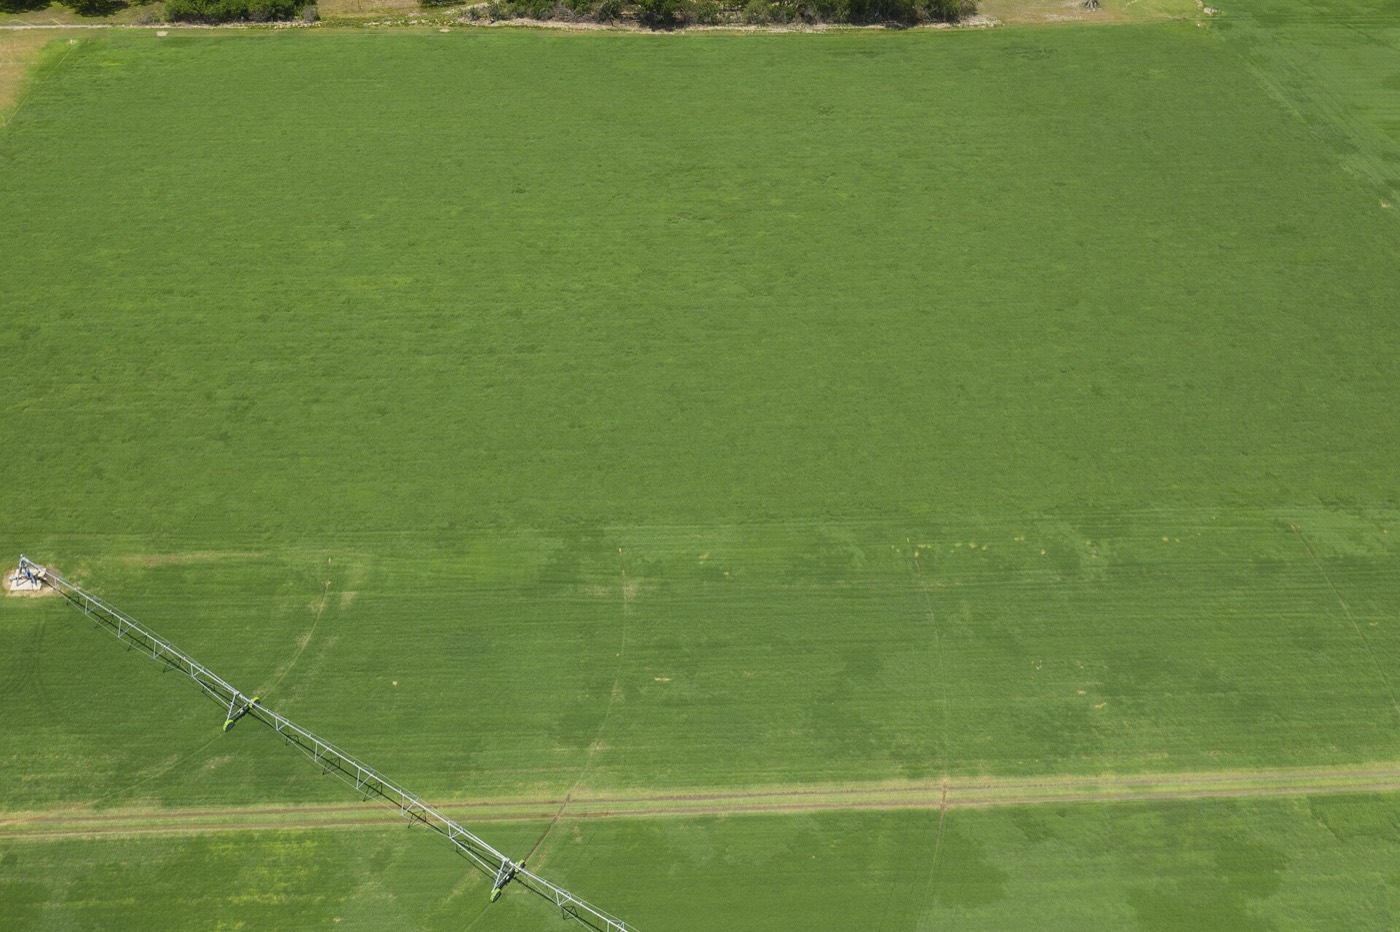
Aerial view of a hayfield with subsurface drip irrigation above and a center pivot field below
Subsurface drip (upper field) next to center-pivot irrigation (lower), Texas. Photo: USDA NRCS, public domain.
1,000+
Hectares in the first phase (2025)
≥3.5 t
CO2e per hectare per year

With Orbia Netafim, the world’s largest precision-irrigation company, farmers in Turkey’s Konya Basin are switching alfalfa, corn and sugar beet fields to subsurface drip irrigation.

Less waterlogged soil and better-placed fertilizer mean less nitrous oxide, and the soil can store more carbon.

Credits under Verra’s VM0042 (Improved Agricultural Land Management) help pay for installing the drip systems.

It builds on Netafim’s drip-irrigated rice credits (2022), which nearly eliminated methane from flooded paddies.

Virridy is Netafim’s exclusive global carbon project developer and offtaker.

Sources: Orbia Netafim and Virridy press release (17 Mar 2025); Virridy press release (16 Sep 2025); virridycarbon.com/turkey.

Check the Arithmetic

1,000 ha × 3.5 t CO2e/ha/yr = 3,500 t CO2e per year in the first phase.

Work through these in pairs (3 minutes):

  1. The Rwanda authorization covers 700,000 t over five years. How many hectares of drip irrigation in Turkey would produce the same?
  2. Which of the two projects is easier to verify, and why? Think about what you can measure directly: water quality at a school tap, or nitrous oxide from a field.
  3. Water-quality credits rely on suppressed demand; soil credits rely on modeled emissions and soil sampling. Which baseline would you trust more?

Answer to 1: 140,000 t/yr ÷ 3.5 t/ha = 40,000 ha.

Who Buys Credits? Data Centers and Embodied Carbon

US data center construction spending

2023
$20.0B
2024
$34.8B
2025
$49.7B

About $85B a year by August 2026. Data centers used 415 TWh of electricity in 2024; the IEA projects about 945 TWh by 2030.

What the largest builders report

  • Microsoft: fiscal 2025 emissions about 57% above 2020, mainly from data center expansion; capital goods are 45% of the total.
  • Google: emissions 81% above 2019; data center construction about 2.3 million t CO2e in 2025.
  • Meta: capital goods about two-thirds of its 8.2 million t Scope 3 (2024).

Where the embodied carbon is (Arup, average of projects)

Upfront (construction)

Structure 30%
Mechanical & electrical 70%

Whole life (equipment replaced 2–3 times)

12%
Mechanical & electrical 88%
~1,500
kg CO2e per m² upfront: a proposed benchmark
~2×
An office building’s embodied carbon

On 100% renewable electricity, operations shrink and embodied carbon becomes the largest source: last week’s whole-life carbon diagram at a much larger scale.

Sources: US Census Bureau, Value of Construction Put in Place (1 Oct 2026); IEA (2025), Energy and AI; Microsoft 2026 Environmental Sustainability Report; Google Environmental Report 2026; Meta 2025 Sustainability Report; Arup (2025), Circular Thinking for Data Centres; Ramboll (2025); MECLA (2026); Alissa et al. (2025), Nature 641:331.

Where a Data Center’s Embodied Carbon Is

Split of embodied carbon (Arup, average of projects)

Upfront (construction)

Structure & building 30%
Mechanical & electrical 70%

Whole life (equipment replaced 2–3 times)

12%
Mechanical & electrical 88%

Within the structure (one 24,000 m² example)

Concrete 61%
Steel 39%

Cement is 7–15% of concrete by weight but 80–95% of its embodied carbon. The servers themselves are counted separately and add more.

~1,500
kg CO2e per m² upfront: a proposed data center benchmark
~2×
An office building’s embodied carbon

On grid electricity, operations can be up to 80% of a data center’s emissions over 60 years. On 100% renewable electricity, operations shrink and the embodied carbon becomes the largest source.

That is last week’s whole-life carbon diagram again, at a much larger scale.

Sources: Arup (2025), Circular Thinking for Data Centres; Ramboll (2025), Developing Sustainable Data Centres; MECLA (2026), The Next Frontier; iMasons Climate Accord (2023), open letter on concrete; Alissa et al. (2025), Nature 641:331.

Reduce First, Then Compensate

Reduce: what builders are doing

  • Microsoft: target of 30% less embodied carbon per design; multi-story designs cut 15–25%; hybrid mass-timber frames up to 35% of structural embodied carbon.
  • Google: construction emissions per MW down 53% from 2019 to 2025; low-carbon steel and concrete cut up to 40%.
  • Amazon: 39 data centers built with lower-carbon concrete in 2025 (113 since 2023).
  • iMasons Climate Accord (250+ companies): asks suppliers for verified Environmental Product Declarations.

Compensate: what is left

Whatever cannot be designed out is emitted before the building opens. Companies cover it with credits:

45 Mt
Carbon removal Microsoft contracted in fiscal 2025
1.3 Mt
Google’s contracted removal portfolio

Discuss: A builder wants to compensate for the concrete and steel in a new data center. Should it buy removals (direct air capture, forests), avoidance credits that also deliver safe water, or both? What does the VCMI guidance in the next section require first?

Sources: Microsoft 2026 Environmental Sustainability Report, pp. 18–21, 33; Google Environmental Report 2026; Amazon 2025 Sustainability Report; iMasons Climate Accord.

Section 2

Integrity & Controversy

Can carbon markets be trusted?

The Reputation Problem

High-Profile Failures

REDD+ over-crediting: A 2023 investigation found that Verra-certified forest protection projects had dramatically over-estimated their impact — more than 90% of rainforest credits “did not represent genuine carbon reductions.”

Source: The Guardian / West et al., Science, 2023

Cookstove scandals: Projects claimed emission reductions based on stove distribution numbers, not actual use. Many stoves sat unused or broken.

Renewable energy additionality: Solar and wind projects in countries where renewables are already cheapest — would they have been built anyway?

Why It Happens

  • Perverse incentives: Project developers profit from more credits, not fewer
  • Auditor conflicts: Verifiers are paid by the projects they audit
  • Baseline manipulation: Inflated baselines = more credits on paper
  • Infrequent verification: Audits happen every 5–7 years; much can change
  • Self-reported data: No independent confirmation of actual usage or impact

The result: Corporate buyers lose trust, prices collapse, and legitimate projects lose funding.

What’s Changed

ICVCM Core Carbon Principles (2023)

The Integrity Council for the Voluntary Carbon Market set 10 principles that credits must meet, including:

  • Robust quantification with conservative baselines
  • Additionality demonstrated with investment or barrier analysis
  • Permanence with risk buffers and insurance
  • No double counting between voluntary and compliance systems
  • Sustainable development benefits assessed and reported

Credits meeting all principles receive the “CCP label”. Digital monitoring of credits is covered in the Lume and dMRV slides.

The Greenwashing Debate

“Is buying carbon credits real climate action, or just paying to pollute?”

The Critique

  • Offsets allow companies to claim “carbon neutral” without actually reducing their own emissions
  • Creates a moral hazard: why invest in costly decarbonization when you can buy $5 credits?
  • Many net-zero pledges rely heavily on offsets rather than direct emission cuts
  • Low-quality credits are effectively worthless

The Defense

  • Not all emissions can be eliminated today — offsets fill the gap
  • VCMI guidelines: companies must first reduce their own emissions by 90%+, then offset the remainder
  • High-quality credits fund real projects with co-benefits (health, livelihoods, ecosystems)
  • Carbon finance is the only scalable revenue mechanism for many developing-country projects

The emerging consensus: Offsets should be a complement to deep decarbonization, not a substitute. The phrase is shifting from “carbon neutral” to “net zero” with strict requirements for own-emission reductions.

Section 3

Do Carbon Markets Work?

What the measured evidence shows, and what else the money pays for

Carbon Pricing Cuts Emissions

Measured effect of introducing a carbon price

Döbbeling-Hildebrandt et al. (2024), Nature Communications 15:4147. Meta-analysis of 483 effect sizes from 80 ex-post studies of 21 carbon pricing schemes.

  • 17 of the 21 schemes produced statistically significant cuts of 5% to 21%, or 4% to 15% after correcting for publication bias.
  • These are early-year effects, mostly at low prices. China’s pilot ETSs cut more than the EU ETS despite much lower prices.
  • EU ETS, French manufacturing 2005–2012: regulated firms cut CO₂ by 14–16% with no detectable drop in output or employment, by investing in lower-emission production. No evidence that emissions moved to unregulated firms.

Colmer, Martin, Muûls & Wagner (2024), Review of Economic Studies, doi:10.1093/restud/rdae055.

Dozens of other pricing schemes have never been evaluated, and the response to today’s higher prices is not yet measured.

Most Offset Credits Overstate Their Impact

Real reductions as a share of credits issued

Probst et al. (2024), Nature Communications 15:9562. Synthesis of 14 studies covering 2,346 projects and almost 1 billion t CO₂e, about one-fifth of all credits issued to date.

<16%
of investigated credits are real reductions
  • HFC-23 destruction came closest, at 68%.
  • Cookstoves were at 11%.
  • Avoided deforestation was at 25%.
  • Wind power and improved forest management showed no statistically significant reductions.

The gap comes from baselines, additionality and self-reported use: the problems in Section 5.

Secondary Benefits: Where the Revenue Goes

Compliance markets raise public money. Most of it is required or chosen to go back into efficiency, household bills, clean energy and resilience.

EU ETS
Over €258 billion in auction revenue from 2013 to 2025, more than €43 billion in 2025 alone. Funds the Innovation Fund and the Modernisation Fund, and since 2025 the Social Climate Fund for households facing higher energy costs.
California cap-and-invest
$15.5 billion implemented since 2014 across 604,891 projects. 76% ($11.4 billion) benefits disadvantaged and low-income communities. Programs cover transit, affordable housing, wildfire and forest health, and other resilience to climate risks.
RGGI (11 northeastern US states)
$856 million invested in 2024, expected to return $2.6 billion in lifetime energy bill savings. Cumulative spending: 54% energy efficiency, 16% direct bill assistance, 11% clean energy, 6% electrification, 6% GHG abatement and climate adaptation. Power-sector CO₂ in the region is about 50% below 2005 while GDP grew.
Adaptation Fund (UN)
Built on a 2% share of credits from the Kyoto Protocol’s Clean Development Mechanism; Article 6.4 sets a 5% share. About $1.6 billion committed since 2010 to 226 local adaptation and resilience projects in developing countries.

Sources: European Commission, What are ETS revenues used for? (2026); CARB, California Climate Investments 2026 Annual Report fact sheet (data to Oct 2025); RGGI, The Investment of RGGI Proceeds in 2024 (June 2026); Adaptation Fund (adaptation-fund.org/about).

Secondary Benefits at the Project Level

Rwanda: carbon-financed water filters and cookstoves

A cluster-randomized trial in Western Province tested a household water filter and improved cookstove program financed by anticipated carbon credits.

−29%
reported diarrhea, children under 5
−25%
reported acute respiratory infection

Kirby et al. (2019), PLOS Medicine 16(6):e1002812. Unblinded; outcomes reported by caregivers.

Two separate ledgers

  • The health benefit and the carbon claim are measured separately. A program can deliver the first while over-crediting the second.
  • Cookstove credits averaged 11% real reductions in Probst et al., although the same kind of program produced the health effects at left.
  • Surveys overstate use. In a separate Rwanda trial, sensors on filters and stoves recorded about 36% less filtered water per day and 40% fewer stove uses per week than surveys and observation reported (Thomas et al. 2013, ES&T 47:13602).

Discussion: should buyers pay for verified health outcomes directly, and price carbon only for what is measured?

Weighing the Evidence

Compliance markets and carbon taxes
  • Measured cuts of 4–15% (bias-corrected) in the early years of 17 schemes
  • EU firms cut 14–16% with no detectable loss of output
  • Raise public revenue, much of it spent on efficiency, bill relief and adaptation
  • A cap does not set where the remaining pollution goes (Lab Part 3)
Voluntary offsets
  • Under 16% of investigated credits are real reductions
  • Results range from 0% (wind, improved forest management) to 68% (HFC-23)
  • Project co-benefits such as child health can be large and measurable
  • Credit quality depends on measured baselines and measured use

For the lab essay: which of these findings would change your answer to “do carbon markets work to address climate change, and for whom?”

Section 4

Climate Finance & Careers

Where the money flows and where you fit in

Voluntary vs. Compliance Markets

~$2B
Voluntary market (2023)
~$900B
Compliance market (2023)
73
Carbon pricing initiatives
23%
Global emissions covered

Compliance Markets

Government-mandated. Companies must participate. Much larger.

  • EU ETS: ~$95/tonne (2023)
  • California cap-and-trade: ~$30/tonne
  • China national ETS (largest by coverage): ~$9/tonne
  • Prices rising as caps tighten

Voluntary Markets

Company-driven. No legal requirement. Smaller but growing.

  • Average price ~$7/tonne (wide range: $1–$600+)
  • Peaked at ~$2B in 2022, contracted in 2023 amid integrity concerns
  • Projected to reach $50B+ by 2030 (TSVCM estimate)
  • Critical funding source for developing-country projects

Article 6 of the Paris Agreement

Article 6 creates the rules for international carbon market cooperation under the Paris Agreement. Finalized at COP26 in Glasgow (2021).

Article 6.2 — Bilateral Trading
Countries can trade emission reductions directly (ITMOs — Internationally Transferred Mitigation Outcomes). Switzerland-Thailand was the first deal. Requires “corresponding adjustments” to avoid double counting between national inventories.
Article 6.4 — Global Carbon Market
A new UN-supervised crediting mechanism replacing the CDM. Open to all countries. Still establishing its methodology framework. Expected to set the global standard for credit quality.
Why It Matters
Article 6 could unlock $250 billion per year in climate finance flows to developing countries. It bridges the gap between national climate pledges and the funding needed to achieve them.

The Role of Concessional Capital

Carbon credit revenue alone cannot fund projects from scratch. The 2–4 year lag before first credits creates a critical financing gap.

Blended Finance Stack

Grants
Philanthropic &
government
+
Concessional Debt
DFIs, impact
investors
+
Carbon Pre-finance
Forward credit
purchase agreements
=
Viable Project
Sustainable
revenue model
  • Philanthropic capital de-risks early-stage projects (R&D, pilot programs)
  • Development finance institutions (IDB, World Bank, USAID) provide low-interest loans and guarantees
  • Advance market commitments guarantee demand for future credits, enabling upfront investment
  • Results-based finance (RBF) ties payments to verified outcomes, not activities

Example: IDB is exploring carbon finance for rural water systems in Latin America (SIRWASH Phase II)

Careers, and Where to Start at CU Boulder

Career paths in carbon markets

Carbon project developer
Design projects, write PDDs, manage the credit lifecycle.
MRV specialist
Build monitoring systems: sensors, satellites, data pipelines.
Third-party auditor (VVB)
Validate and verify projects for Gold Standard and Verra.
Climate finance analyst
Structure deals, model carbon revenue, evaluate portfolios at banks, DFIs and carbon funds.
Sustainability consultant
Help companies set net-zero targets under VCMI and SBTi.
Registry or standards body
Write methodologies and market rules at ICVCM, Verra, Gold Standard, UNFCCC.

At CU Boulder

Mortenson Center in Global Engineering
Engineering, sustainability and global development. Home of this course.
Virridy
CU Boulder spinout founded and led by Prof. Thomas: the Lume sensor and carbon-financed water programs.
RASEI
Joint institute with NREL on renewable energy and decarbonization.
Getting involved
Undergraduate research, Mortenson Center design projects, Engineers Without Borders, Virridy internships.

CU Boulder Connections

Mortenson Center in Global Engineering
Research and education at the intersection of engineering, sustainability, and global development. Home of this course.
Virridy
CU Boulder spinout company. Develops the Lume IoT sensor for water quality monitoring and carbon credit verification. Carbon-financed drinking water programs in six African countries and a precision-irrigation program in Turkey. Founded and led by Prof. Thomas.
RASEI (Renewable & Sustainable Energy Institute)
Joint institute between CU Boulder and NREL. Research on renewable energy systems, grid integration, and decarbonization pathways.
Getting Involved
Undergraduate research opportunities, Mortenson Center Design Projects, Engineers Without Borders, RASEI seminars, Virridy internships.
Section 5 · Lab

Carbon Markets on Trial

Do carbon markets work to address climate change, and for whom?

The Lab at a Glance

You test carbon pricing from four directions with four public tools: whether it cuts emissions, who pays, where the pollution goes, and where the money goes. Then you write a short essay answering the lab’s question with your own results.

Part 1
Emissions · 20 pts
Part 2
Who pays · 20 pts
Part 3
Pollution · 20 pts
Part 4
Money · 15 pts
Part 5
Essay · 25 pts

Individual assignment, 6.7% of the course grade (100 points, entered in Canvas as 10). It builds on the En-ROADS lab, where you set a global carbon price with a slider.

Key dates

Thu Nov 12Lab released
Tue Nov 17Carbon markets lecture (today’s slides)
Dec 1 & 3No lecture: class time is lab work time with tutoring
Fri Dec 4Report due on Canvas, 11:59 pm

Full lab instructions →

Part 1: Does a Carbon Tax Cut Emissions? 20 pts

Tool: U.S. Energy Policy Simulator (Energy Innovation), live at left.

  1. Run business as usual; record US emissions in 2030, 2040, 2050.
  2. Add an economy-wide carbon tax. Choose and justify a price path.
  3. Reset. Build a package without a carbon tax (clean electricity, vehicle standards, building codes, methane rules) that reaches about the same 2050 emissions.
  4. Compare emissions, premature deaths avoided, and cost. One figure per scenario.

Answer: Which costs less per ton avoided? Which could pass Congress? Why has the US relied on standards and subsidies instead of a carbon price?

Parts 2 and 3: Who Pays, and Where Does the Pollution Go?

Part 2 · Who pays? (20 pts)

Tool: RFF Carbon Pricing Calculator

Use a price close to Part 1. Compare at least three uses of the revenue (equal household dividends, payroll or income tax cuts, deficit reduction). Record the change in well-being by income quintile, plus emissions and revenue: one table, one chart.

Answer: Which revenue use protects the lowest-income households? Which helps the economy most? Canada returned most of its carbon tax revenue as rebates and still repealed the consumer tax in 2025. What does that tell you?

Part 3 · Where does the pollution go? (20 pts)

Tool: CARB Pollution Mapping Tool with the CalEnviroScreen 4.0 layer

Filter to cap-and-trade facilities and turn on the SB 535 disadvantaged-communities layer. Pick six facilities in one sector, three inside and three outside those communities. Plot greenhouse gases and PM2.5 or NOx over time.

Answer: Did emissions near disadvantaged communities fall faster or slower? Compare with Cushing et al. (2018). What does a cap not guarantee for the people next door?

Part 4: Where Does the Money Go? 15 pts

Tool: Berkeley Voluntary Registry Offsets Database: every project, issuance and retirement on the six major voluntary registries (Excel download).

  1. Choose one project type common in low- and middle-income countries: REDD+, cookstoves or household water treatment.
  2. Report credits issued and retired, in which countries, and the largest buyers where the data show them.
  3. Read one project’s registry page: who developed it, who lives in the project area, what benefits are claimed for them.

Answer: Using West et al. (2023) or Gill-Wiehl et al. (2024), how confident can a buyer be that one credit equals one ton? If a credit overstates the carbon, can the money reaching at-risk communities still be worth it? Who should decide?

Amazon rainforest
REDD+
Improved cookstove
Cookstoves
Community water filter
Water treatment

Water treatment is the category in today’s Virridy case study. If you choose it, you may not use Virridy’s own materials as your evidence of quality; use the registry record and the independent literature.
Part 5 and the Report

Part 5: Do carbon markets work? (25 pts)

A one-to-two page essay using your results from Parts 1–4:

  • Do carbon prices and credits reduce emissions, by your evidence?
  • Why has the US not adopted a national carbon tax, and would you support one? With what revenue use, and what protections for overburdened communities?
  • The strongest case for carbon markets, and the strongest case against them, on environmental justice grounds.

Using Claude

Use it to learn the tools, explain mechanisms and test arguments. The runs, downloads and numbers must be your own; check every citation. End with a 2–3 sentence AI Use Statement.

Report format

  • One PDF, five sections, references, AI Use Statement.
  • Every number from your own runs, with tool version or download date and settings, so someone else can reproduce it.
  • Figures with labeled axes and a one-sentence caption.
Grade per partStandard
100%Results accurate and reproducible; every question answered using them
50–75%Results missing or not reproducible, or answers not drawing on them
0%Not attempted

Readings: Green (2021) ERL; Klenert et al. (2018) Nat. Clim. Change; Mildenberger et al. (2022) Nat. Clim. Change; Cushing et al. (2018) PLOS Med.; West et al. (2023) Science; Gill-Wiehl, Kammen & Haya (2024) Nat. Sustain.; World Bank Carbon Pricing Dashboard.

Key Takeaways

  • Carbon markets put a price on pollution — creating economic incentives to reduce emissions through either compliance mandates or voluntary action.
  • Credit integrity depends on additionality, permanence, and accurate monitoring — concepts that are technically and philosophically complex.
  • The water sector is massively under-represented in carbon finance despite contributing 10% of emissions and having 1.6 billion credits/year of potential.
  • Self-reported data overestimates usage by 36–40% — digital MRV with IoT sensors is essential for market credibility.
  • Offsets should complement, not substitute for direct emission reductions. The market is evolving toward higher integrity standards.
  • Climate finance is a growing career field that needs engineers who understand both the technology and the economics.

Discussion Questions

1. Should a company be allowed to claim “net zero” if it offsets 50% of its emissions with carbon credits rather than reducing them directly?

2. Is suppressed demand a legitimate basis for carbon credits, or does it create a perverse incentive to keep communities energy-poor?

3. A REDD+ project protects a forest from logging, but the logging company moves to the next unprotected forest. Has the project achieved anything?

4. If IoT sensors show that actual product usage is 40% lower than self-reported, what are the ethical implications for projects that have already issued credits based on surveys?

5. How should we value a carbon credit that also provides clean drinking water vs. one that only removes CO₂? Should co-benefits affect the price?

Imported

Global Water Security: Analytics to Action

Keynote slides, imported for consolidation

Global Water Security Analytics to Action
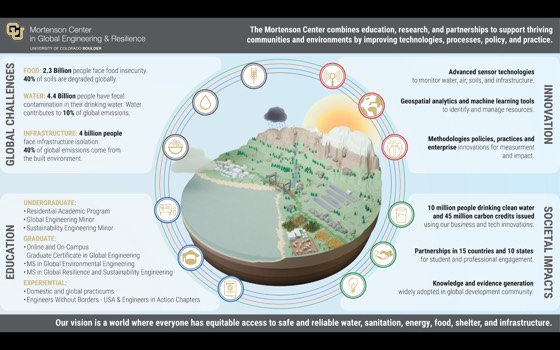
Slide 6 · GHC displayed-1 · Mortenson Center Overview
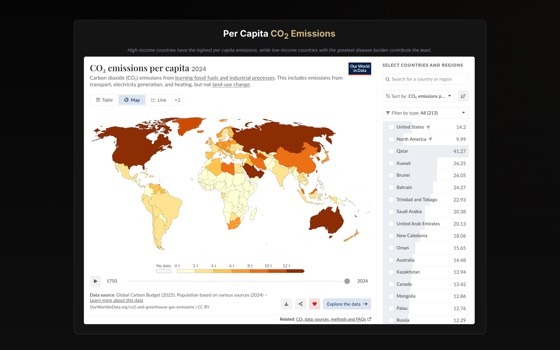
Per Capita CO 2 Emissions
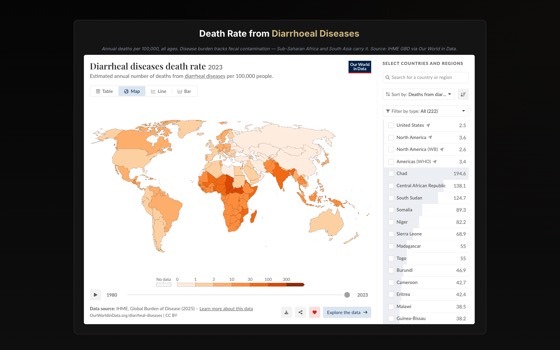
Death Rate from Diarrhoeal Diseases
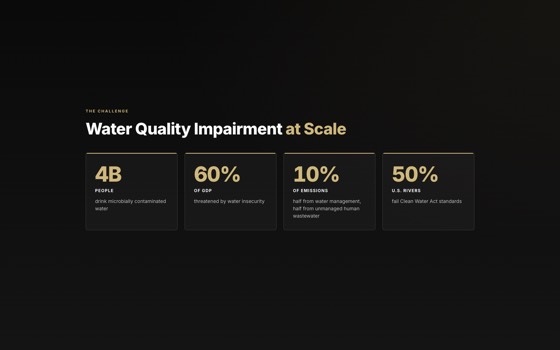
Water Quality Impairment at Scale
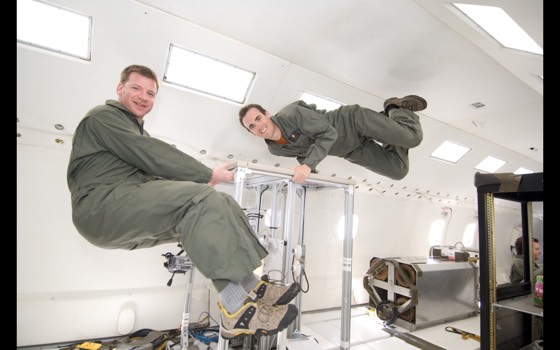
MIT-5 · NASA Reduced Gravity Aircraft
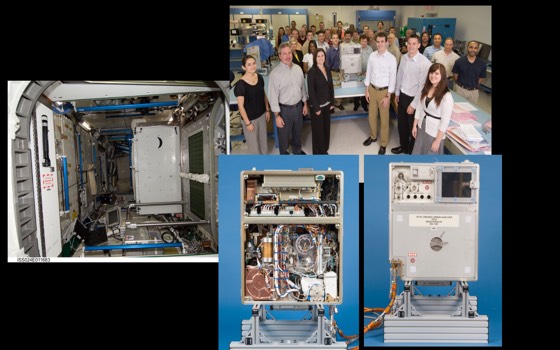
MIT-7 · Four-photo collage (positions from PPTX)
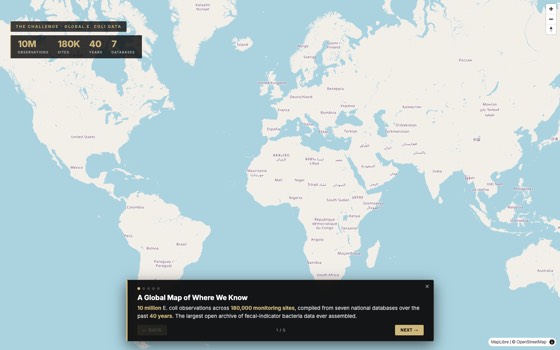
Slide 3 · Challenge / global map
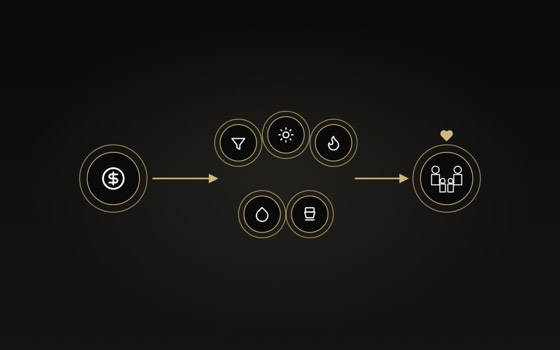
Slide 4-linear · Conventional Model: Money → Technology → Family (linear)
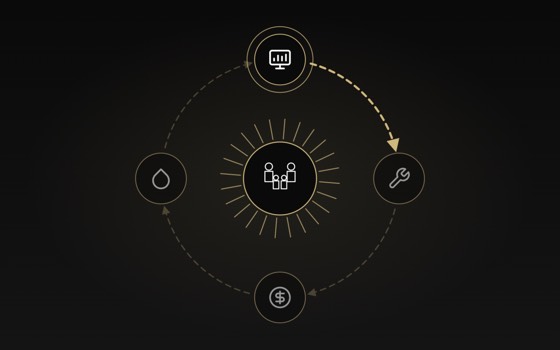
Slide 4 · Pillar 1 · Accountability Loop (animated)
The Drinking Water Credit Model
Credit Economics
High Integrity Water Projects Across Africa
Slide 14
Slide 15
Slide 16
Slide 17
Slide 16b · Liters Per Day — animated HTML recreation of BarGraphCupsSlower.mp4
MIT-27 · Field Program Health Outcomes
Slide 25c · Amazi Meza School Water Quality · Rwanda
Slide 21
Slide 17b · Water Pump Functionality (animated HTML chart)
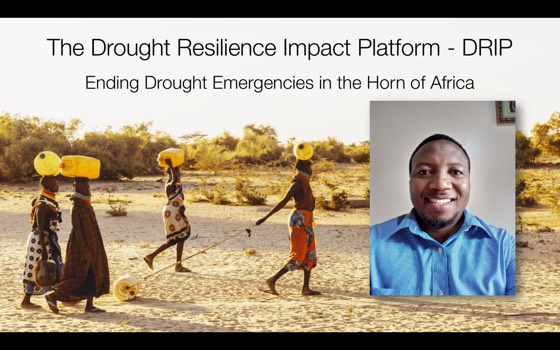
Slide 23
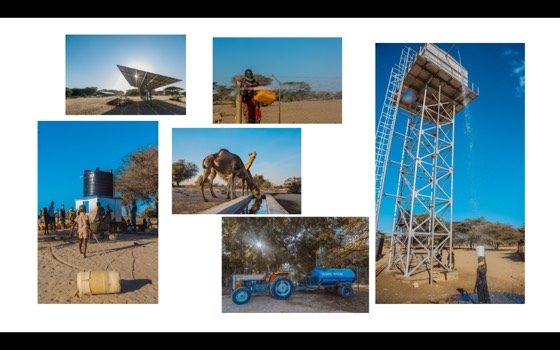
Slide 24
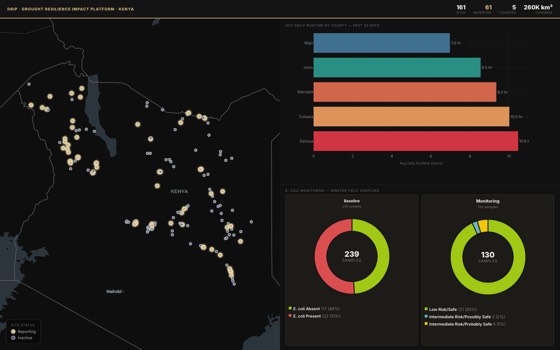
Slide 25b · DRIP Kenya Live Dashboard (native)
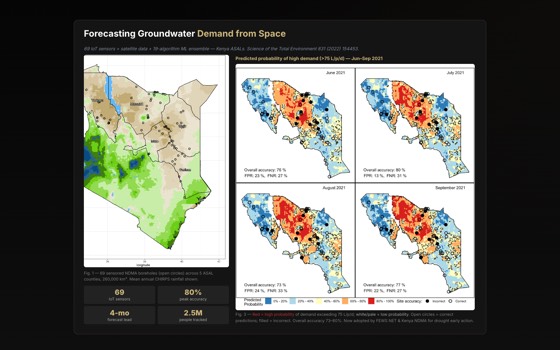
Forecasting Groundwater Demand from Space
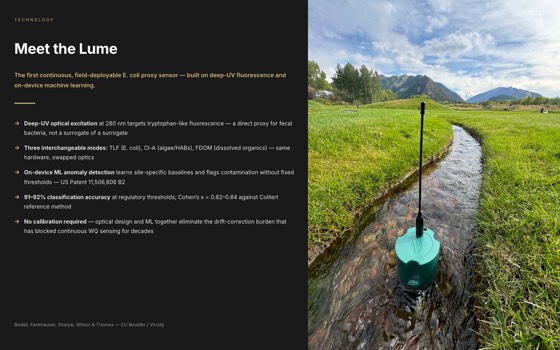
Meet the Lume
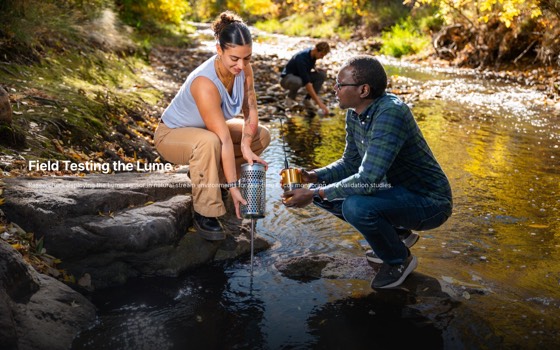
Field Testing the Lume
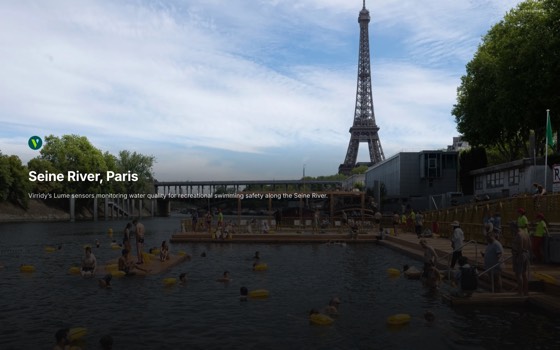
Seine River, Paris
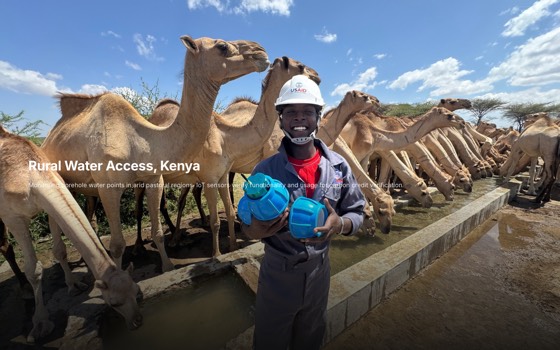
Rural Water Access, Kenya
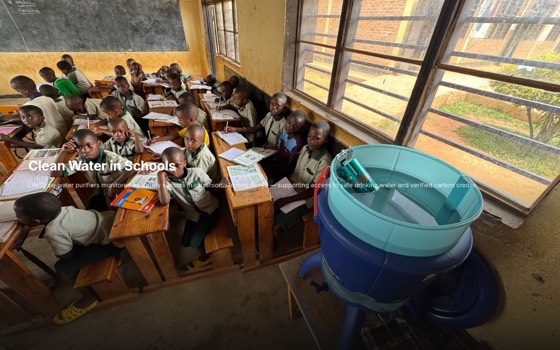
Clean Water in Schools
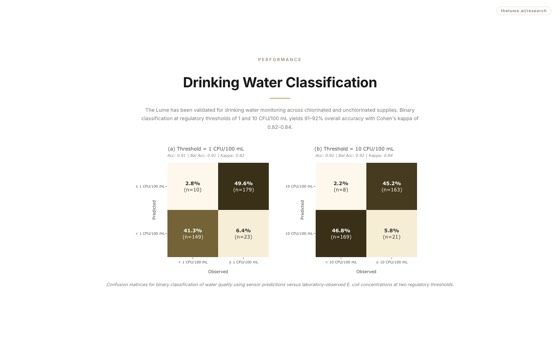
Drinking Water Classification
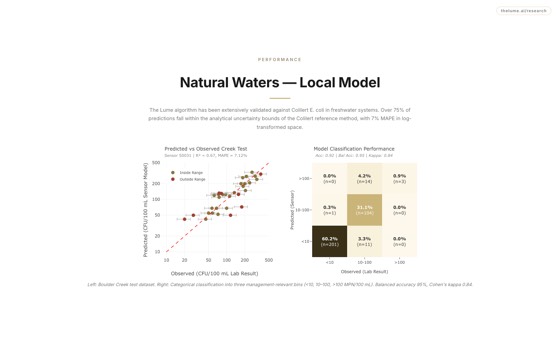
Natural Waters — Local Model
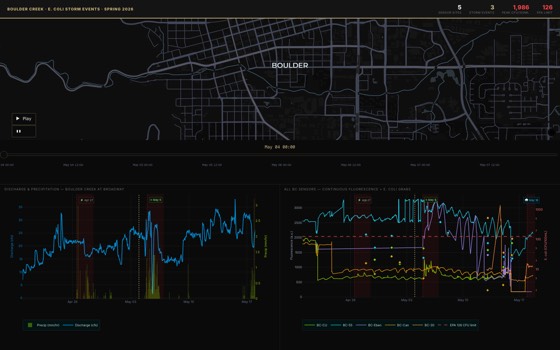
Slide 25d · Boulder Creek E. coli Storm Events
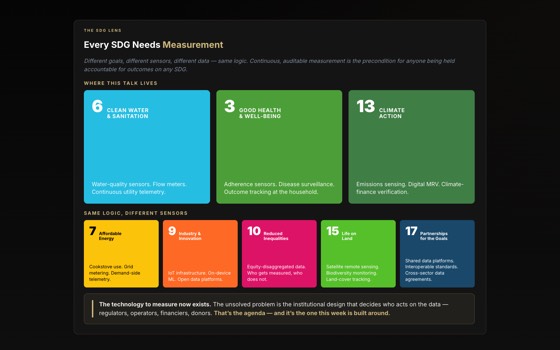
Every SDG Needs Measurement
Global Water Security Analytics to Action
Drag to reorder · × to delete